The Jeanbrun Scheme: How Depreciation Changes the Maths of a Buy-to-Let Purchase
As the successor to the Pinel scheme, the Jeanbrun scheme doesn't work the same way. Where Pinel offered a tax reduction, Jeanbrun acts further upstream, on the taxable base itself. For an investor, that distinction changes everything — provided you understand it properly.
By Bénie RollandPublished on Updated on
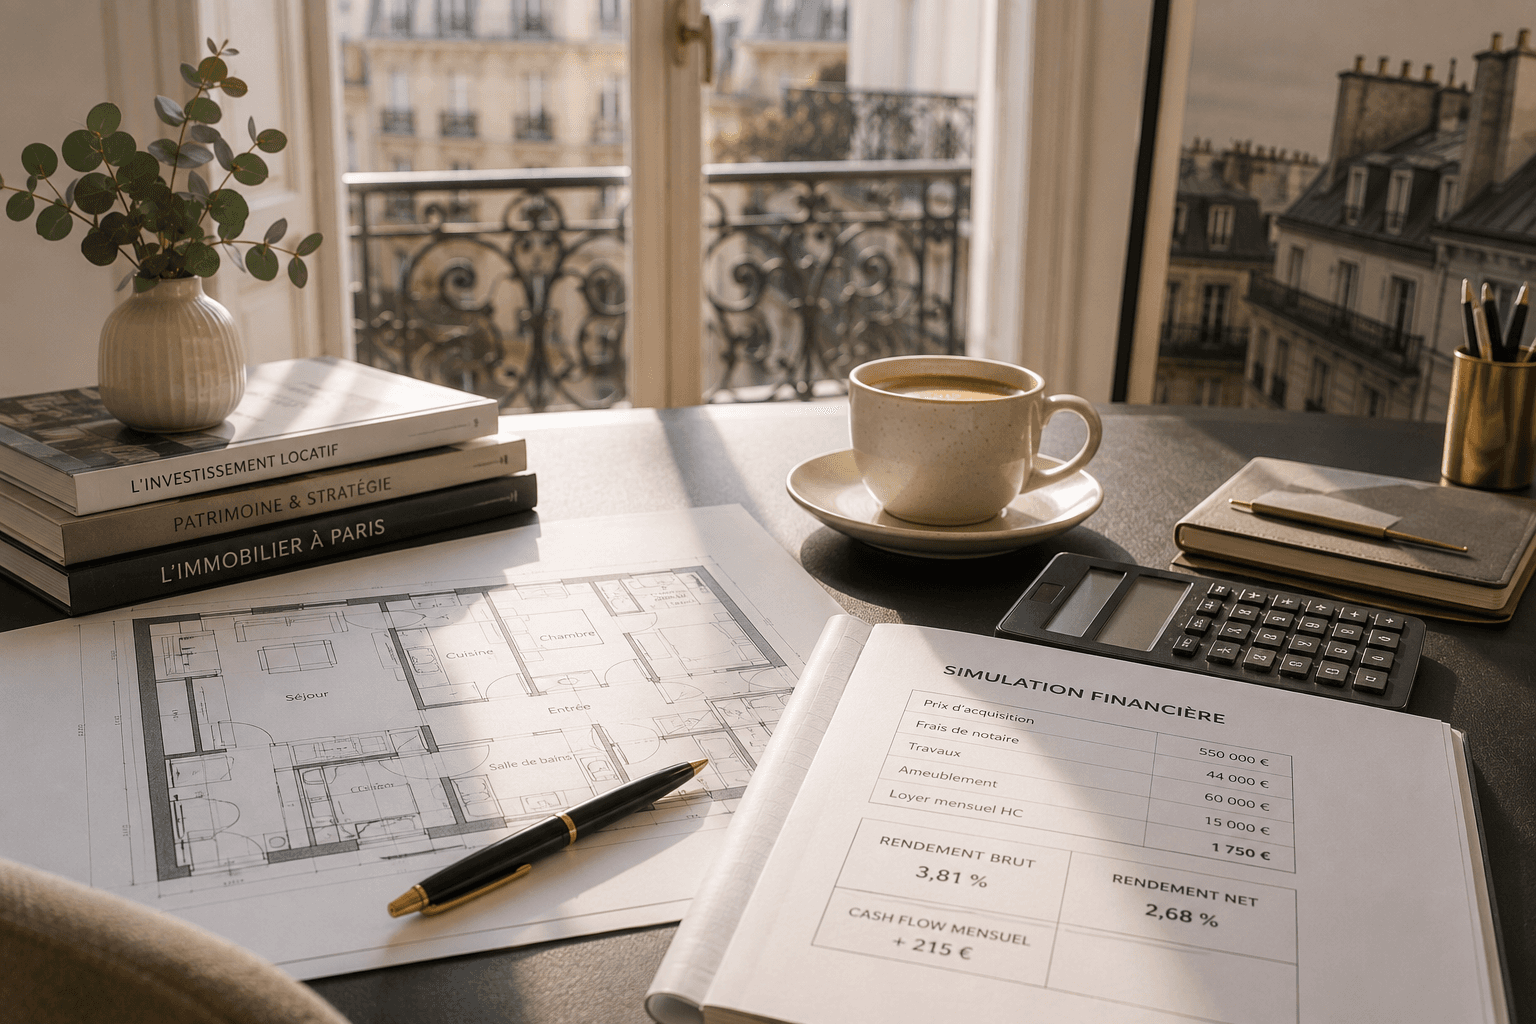
Since the Pinel scheme ended on 1 January 2025, investors have been looking for a new framework. The 2026 Finance Act created one: the private landlord status, known as the Jeanbrun scheme, which came into force on 21 February 2026. It is currently being fine-tuned as part of the Relance Logement (Housing Recovery) bill. Here's how it works, and why it changes the maths of a buy-to-let purchase.
The principle: depreciate, don't reduce
The Pinel scheme granted a flat-rate tax reduction. The Jeanbrun scheme, by contrast, allows you to depreciate the property for tax purposes: each year, you deduct a fraction of the property's value from your rental income, in the same way a company depreciates an asset.
In practical terms: you can depreciate up to 80% of the property's value (the building itself, excluding land value), over a minimum letting commitment of 9 years, for an unfurnished let used as a main residence.
Why this distinction matters so much
Depreciation reduces your taxable base, not your tax bill directly. The actual saving therefore depends on your marginal tax rate (TMI, tranche marginale d'imposition): the higher it is, the greater the benefit.
As a rough guide, including social security contributions: at a marginal tax rate of 30%, every euro depreciated generates around €0.47 in savings; at 41%, around €0.58. The scheme is therefore particularly well suited to taxpayers on 30% or higher.
✅ Key takeaway: Jeanbrun rewards existing rental income and high marginal tax rates. If you're already a landlord or heavily taxed, depreciation can wipe out a large share of the tax on your rental income.
The trade-offs and limits
The benefit comes at a price: commitments to be honoured.
- Rent caps: rent must stay below a ceiling; the more modest it is, the higher the depreciation allowed (a bonus of between 3.5% and 5.5% depending on the level).
- Unfurnished lets only: the scheme targets unfurnished lets taxed as rental income (revenus fonciers). It cannot be combined, for the same property, with furnished letting (LMNP), the Denormandie scheme, the Malraux scheme or Loc'Avantages.
- Maximum of 2 properties per tax household; detached houses are excluded.
- An irrevocable commitment: should you breach the terms (early sale, exceeding the rent cap, letting to a relative), the tax benefit is clawed back.
⚠️ The point to watch: The rent cap is at the heart of the trade-off. Accepting a capped rent in exchange for the depreciation benefit is only worthwhile if the overall sum – tax savings versus lost rental income – comes out positive. In Paris, where rent control already applies, this calculation deserves a precise simulation.
A point to watch: the text is still evolving
The Relance Logement bill is adjusting the Jeanbrun scheme – notably lowering the entry threshold for renovated older properties. Several parameters (depreciation rate, caps, commitment period, combination with the property-loss deficit mechanism) may still change as parliamentary debate continues. Any simulation should therefore be redone once the text is finally adopted.
Worth knowing: the scheme is accessible via a family SCI (property-holding company) subject to income tax, which allows depreciation to be combined with estate planning – whereas an SCI subject to corporation tax is excluded.
The APPARTE analysis
The Jeanbrun scheme shifts the yardstick for profitability: a property can become attractive because of its tax treatment as much as its price. But the benefit isn't automatic – it has to be calculated, factoring in marginal tax rate, rent cap, cost of works, and holding period. We factor this into our analysis of any property intended for letting, in light of your tax situation, to separate the real saving from the marketing pitch. A good buy-to-let purchase is the right property, at the right price, within the right tax framework.
APPARTE factors tax considerations into every buy-to-let purchase
Jeanbrun depreciation, rent caps, Paris rent control: we assess the real return on a property in light of your situation. Book an appointment.
General information accurate as at the date of publication; this does not constitute tax or legal advice. The scheme may change as the Relance Logement bill progresses. Any decision should be based on a personalised simulation validated by a professional (chartered accountant, notaire, or wealth management adviser).
Read next
Three articles to go further.
Off-Market Property in Paris: The Truth Behind the Myth
Off-market property in Paris is often oversold. Discover the reality of this hidden market and how APPARTE helps you find the ideal property.
Mortgage Rates in 2026: Buy or Wait? The APPARTE Analysis
Mortgage rates in 2026, buy or wait? Discover our analysis to make the right property decision in Paris and Île-de-France without speculating.
Rent Control in Paris: What the End of the Trial Scheme in November 2026 Means for Your Investment
A new prefectural order (arrêté) has set reference rents in Paris since 1 July 2026. But the scheme, inherited from the ELAN law, is due to expire on 23 November. Between annual renewal and political uncertainty, here's how to calmly factor this deadline into your acquisition strategy.